Posts Tagged ‘ risk ’

Communicating Risk and Uncertainty

January 20, 2015
By
Communicating Risk and Uncertainty

David Spiegelhalter gave a fascinating talk on Communicating Risk and Uncertainty to the Public & Policymakers at the Grantham Institute of the Imperial College in London last Tuesday.In a very engaging way David gave many examples and anecdotes fr...
Read more »

Effective risk management with R

September 21, 2014
By
Effective risk management with R

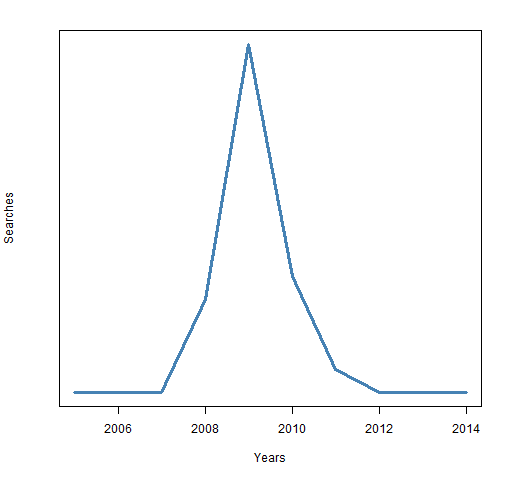
Conference The first EARL Conference (Effective Applications of the R Language) was held 2014 September 15-17 in London. Talk My talk was “Effective risk management with R” (annotated slides). Instability hypothesis When I was preparing for the talk, one of my ideas was to show the Google trend for searches for Minsky’s instability hypothesis.  I … Continue reading →

Read more »

Guest Post: Risk, Insurance and the Actuary

December 3, 2013
By
Guest Post: Risk, Insurance and the Actuary

Risk, Insurance, and the Actuary Risk is an inherent part of our daily life. As a result, most of us, take out insurance policies as a means of protection against scenarios which, were they to occur, may cause hardship whether … Continue reading →

Read more »

Historical Value at Risk versus historical Expected Shortfall

November 18, 2013
By
Historical Value at Risk versus historical Expected Shortfall

Comparing the behavior of the two on the S&P 500. Previously There have been a few posts about Value at Risk (VaR) and Expected Shortfall (ES) including an introduction to Value at Risk and Expected Shortfall. Data and model The underlying data are daily returns for the S&P 500 from 1950 to the present. The VaR and … Continue reading →

Read more »

Predictive Modeling

November 11, 2013
By
Predictive Modeling

Tomorrow, around noon, I will be giving a talk on predictive modeling for actuaries. In the introduction, I will get back shortly on the idea that a prediction is usually a best estimate, in the sense of getting an expected value. And because it is natural to use least square ideas. In order to illustrate all those concepts, we will use a simple dataset, with the sex, the height and…

Read more »

Why models need a certain culture to flourish

October 8, 2013
By
Why models need a certain culture to flourish

About half a year ago Ian Branagan, Chief Risk Officer of Renaissance Re - a Bermudian reinsurance company with a focus on property catastrophe insurance, gave a talk about the usage of models in risk management and how they evolved over the last twent...

Read more »

Changeability of Value at Risk estimators

August 26, 2013
By
Changeability of Value at Risk estimators

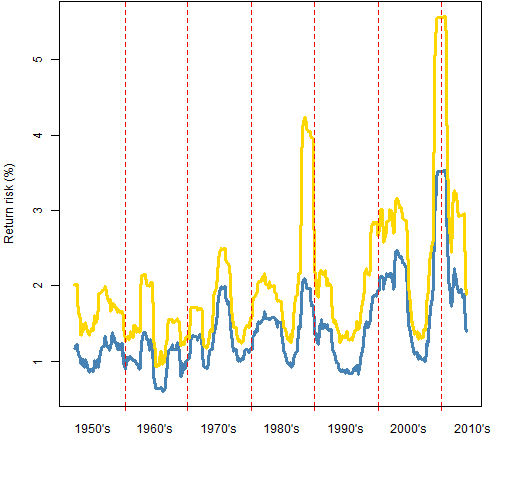
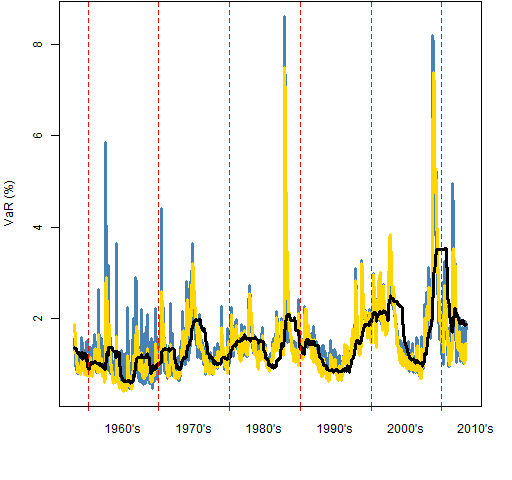
How does Value at Risk change through time for the same portfolio? Previously There has been a number of posts on Value at Risk, including a basic introduction to Value at Risk and Expected Shortfall. The components garch model was also described. Issue The historical method for Value at Risk is by far the most commonly … Continue reading →

Read more »

Las Vegas and financial institutions

August 21, 2013
By
Las Vegas and financial institutions

Exactly one month ago, I entered the Bellagio casino to gamble at the roulette. It was actually a request from my daughter’s godfather (who happens to be a probabilist, actually). On a comment on a previous post, he suggested the following deal, In the Bellagio you put 10$ for me on the 33 and 10$ for you as well. If 33 shows up, you bring me to a French “3…

Read more »

The scaling of Expected Shortfall

June 16, 2013
By
The scaling of Expected Shortfall

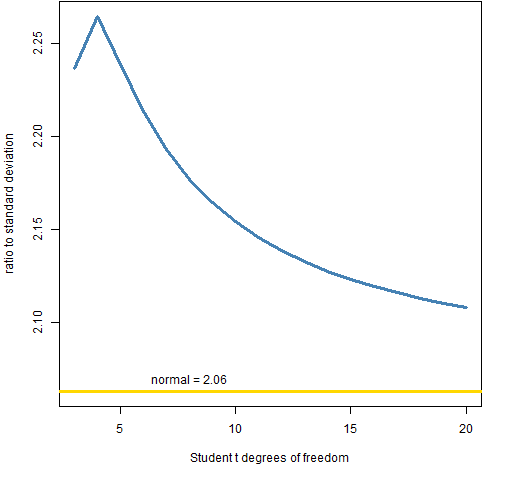
Getting Expected Shortfall given the standard deviation or Value at Risk. Previously There have been a few posts about Value at Risk and Expected Shortfall. Properties of the stable distribution were discussed. Scaling One way of thinking of Expected Shortfall is that it is just some number times the standard deviation, or some other number … Continue reading →

Read more »

Value at Risk with exponential smoothing

May 28, 2013
By
Value at Risk with exponential smoothing

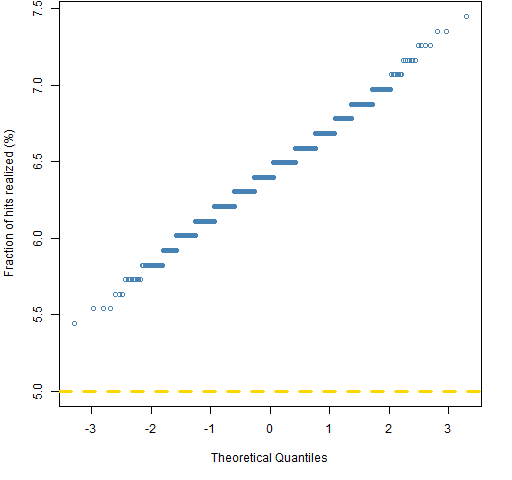
More accurate than historical, simpler than garch. Previously We’ve discussed exponential smoothing in “Exponential decay models”. The same portfolios were submitted to the same sort of analysis in “A look at historical Value at Risk”. Issue Markets experience volatility clustering.  As the previous post makes clear, historical VaR suffers dramatically from this.  An alternative is … Continue reading →

Read more »


Subscribe

Email:

  Subscribe