
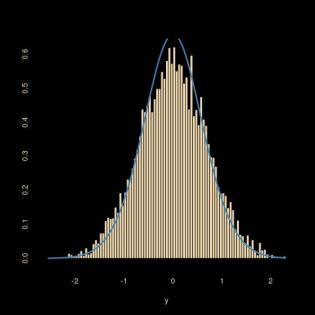
Simulating a bivariate normal under the constraint (or conditional to the fact) that x²-y²=1 (a non-linear zero measure curve in the 2-dimensional Euclidean space) is not that easy: if running a random walk along that curve (by running a random walk on y and deducing x as x²=y²+1 and accepting with a Metropolis-Hastings ratio based […]


