Posts Tagged ‘ Trading Strategies ’

Linking R to IQFeed with the QuantTools package

June 4, 2017
By
Linking R to IQFeed with the QuantTools package

IQFeed provides streaming data services and trading solutions that cover the Agricultural, Energy and Financial marketplace. It is a well known and recognized data feed provider geared toward retail users and small institutions. The subscription price starts at around $80/month. Stanislav Kovalevsky has developed a package called QuantTools. It is an all in one package designed to enhance quantitative […]

Read more »

BERT: a newcomer in the R Excel connection

November 30, 2016
By
BERT: a newcomer in the R Excel connection

A few months ago a reader point me out this new way of connecting R and Excel. I don’t know for how long this has been around, but I never came across it and I’ve never seen any blog post or article about it. So I decided to write a post as the tool is really […]

Read more »

Trading strategy: Making the most of the out of sample data

August 19, 2016
By
Trading strategy: Making the most of the out of sample data

When testing trading strategies a common approach is to divide the initial data set into in sample data: the part of the data designed to calibrate the model and out of sample data: the part of the data used to validate the calibration and ensure that the performance created in sample will be reflected in the […]

Read more »

Introducing fidlr: FInancial Data LoadeR

April 21, 2016
By
Introducing fidlr: FInancial Data LoadeR

fidlr is an RStudio addin designed to simplify the financial data downloading process from various providers. This initial version is a wrapper around the getSymbols function in the quantmod package and only Yahoo, Google, FRED and Oanda are supported. I will probably add functionalities over time. As usual with those things just a kind reminder: “THE SOFTWARE […]

Read more »

Maintaining a database of price files in R

December 13, 2015
By
Maintaining a database of price files in R

Doing quantitative research implies a lot of data crunching and one needs clean and reliable data to achieve this. What is really needed is clean data that is easily accessible (even without an internet connection). The most efficient way to do this for me has been to maintain a set of csv files. Obviously this […]

Read more »

Factor Evaluation in Quantitative Portfolio Management

March 23, 2015
By
Factor Evaluation in Quantitative Portfolio Management

When it comes to managing a portfolio of stocks versus a benchmark the problem is very different from defining an absolute return strategy. In the former one has to hold more stocks than in the later where no stocks at all can be held  if there is not good enough opportunity.  The reason for that is the tracking error. This […]

Read more »

Risk as a “Survival Variable”

December 8, 2014
By
Risk as a “Survival Variable”

I come across a lot of strategies on the blogosphere some are interesting some are a complete waste of time but most share a common feature: people developing those strategies do their homework in term of analyzing the return but much less attention is paid to the risk side its random nature. I’ve seen comment like “a […]

Read more »

A Simple Shiny App for Monitoring Trading Strategies – Part II

August 7, 2014
By

This is a follow up on my previous post “A Simple Shiny App for Monitoring Trading Strategies“.  I added a few improvements that make the app a bit better (at least for me!). Below is the list of new features : A sample  .csv file (the one that contains the raw data) A “EndDate”  drop […]

Read more »

Adjusted Momentum

August 1, 2014
By
Adjusted Momentum

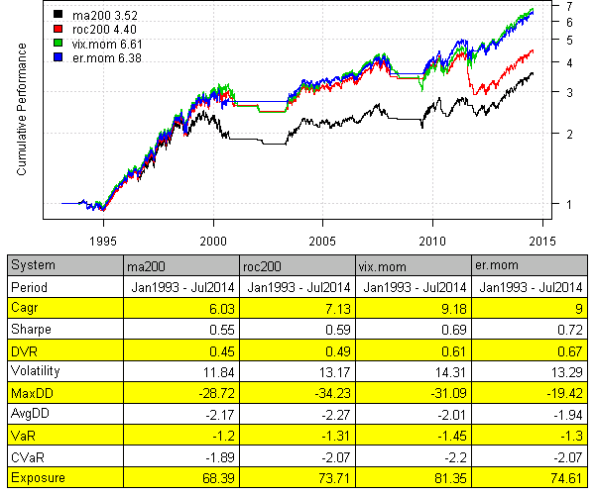
David Varadi has published two excellent posts / ideas about cooking with momentum: VIX-Adjusted Momentum Error-Adjusted Momentum I just could not resist the urge to share these ideas with you. Following is implementation using the Systematic Investor Toolbox. Please enjoy and share your ideas with David and myself. To view the complete source code for […]

Read more »

A Simple Shiny App for Monitoring Trading Strategies

June 25, 2014
By
A Simple Shiny App for Monitoring Trading Strategies

In a previous post I showed how to use  R, Knitr and LaTeX to build a template strategy report. This post goes a step further by making  the analysis  interactive. Besides the interactivity, the Shiny App also solves two problems : I can now access all my trading strategies from a single point regardless of the instrument traded. […]

Read more »


Subscribe

Email:

  Subscribe