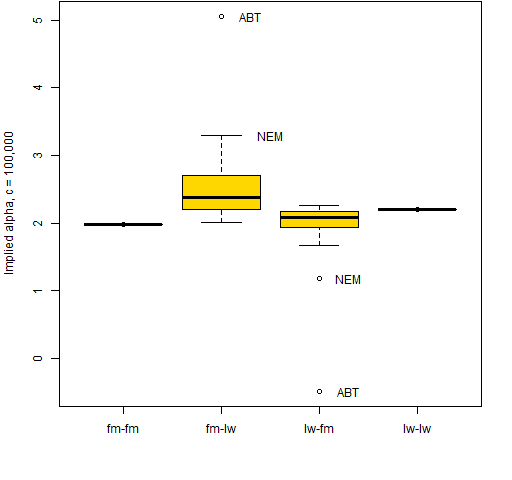
Posts Tagged ‘ Quant finance ’

A complicated answer to a simple correlation question

February 9, 2014
By
A complicated answer to a simple correlation question

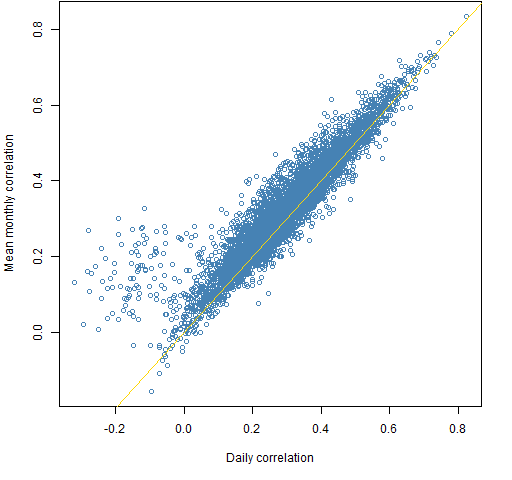
A data analysis surprise party. Simple question If I have correlation matrices each estimated with a month of daily returns, how much worse is the average of six of those compared to the estimate with six months of daily data? Expected answer Do a statistical bootstrap with the returns and compare the standard deviations across … Continue reading →
Read more »

garch models caught in the spotlight

January 13, 2014
By

An attempt to clarify the basics. Previously There have been several posts about garch.  In particular: A practical introduction to garch modeling The components garch model in the rugarch package Genesis A reader emailed me because he was confused about the workings of garch in general, and simulation with the empirical distribution in particular. If … Continue reading →

Read more »

Further adventures with higher moments

December 23, 2013
By
Further adventures with higher moments

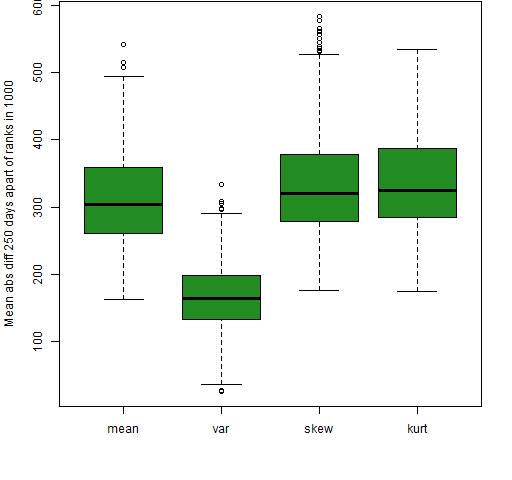
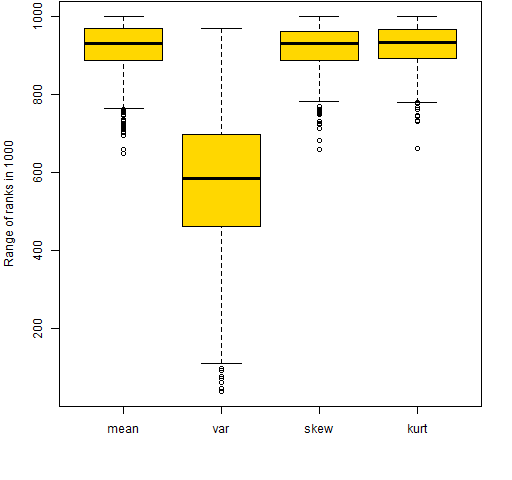
Additional views of the stability of skewness and kurtosis of equity portfolios. Previously A post called “Four moments of portfolios” introduced the idea of looking at the stability of the mean, variance, skewness and kurtosis of portfolios through time. That post gave birth to a presentation at the London Quant Group. That talk gave birth … Continue reading →

Read more »

Quant finance blogs

October 22, 2013
By

What I’ve learned from updating the blogroll. New entries The easy option is to go to The Whole Street which aggregates lots of quant finance blogs. Somehow Bookstaber missed out being on the blogroll before — definitely an oversight. Timely Portfolio was another that I was surprised wasn’t already there. The R Trader talks about … Continue reading →

Read more »

Four moments of portfolios

October 14, 2013
By
Four moments of portfolios

What good are the skewness and kurtosis of portfolios? Previously The post “Cross-sectional skewness and kurtosis: stocks and portfolios” looked at skewness and kurtosis in portfolios.  The key difference between that post and this one is what distribution is being looked at. The previous post specified a single time and looked at the distribution across … Continue reading →

Read more »

The look of verifying data

October 7, 2013
By
The look of verifying data

Get data that fit before you fit data. Why verify? Garbage in, garbage out. How to verify The example data used here is daily (adjusted) prices of stocks.  By some magic that I’m yet to fathom, market data can be wondrously wrong even without the benefit of the possibility of transcription errors.  It doesn’t seem … Continue reading →

Read more »

Introduction to stable distributions for finance

June 10, 2013
By
Introduction to stable distributions for finance

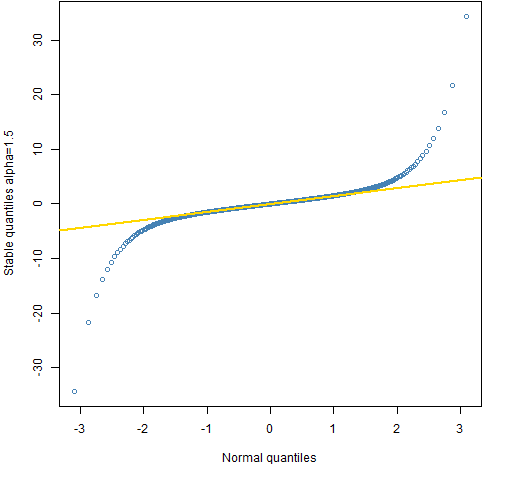
A few basics about the stable distribution. Previously “The distribution of financial returns made simple” satirized ideas about the statistical distribution of returns, including the stable distribution. Origin As “A tale of two returns” points out, the log return of a long period of time is the sum of the log returns of the shorter … Continue reading →

Read more »

Implied alpha and minimum variance

May 20, 2013
By
Implied alpha and minimum variance

Under the covers of strange bedfellows. Previously The idea of implied alpha was introduced in “Implied alpha — almost wordless”. In a comment to that post Jeff noticed that the optimal portfolio given for the example is ever so close to the minimum variance portfolio.  That is because there is a problem with the example … Continue reading →

Read more »

Variance matrix differences

May 15, 2013
By
Variance matrix differences

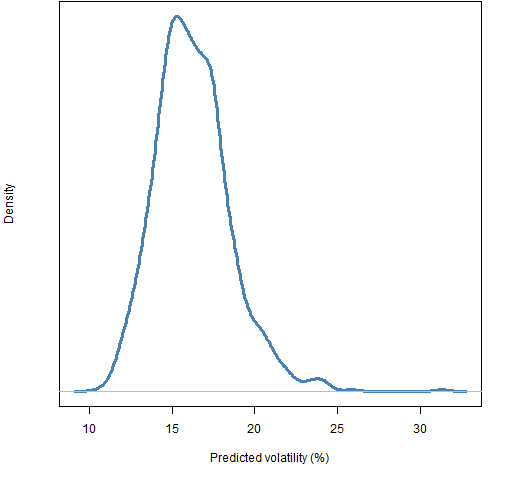
Torturing portfolios to give different volatilities between a factor model and Ledoit-Wolf shrinkage. Previously There have been posts on: “What the hell is a variance matrix?” factor models Ledoit-Wolf shrinkage Question Two of the several ways to produce an estimate of the variance matrix of asset returns is a statistical factor model and Ledoit-Wolf shrinkage.  … Continue reading →

Read more »

The half variance approximation for mean returns

May 6, 2013
By
The half variance approximation for mean returns

What’s that thing about arithmetic and geometric returns and the variance? Previously An introduction to the difference between simple and log returns is: A tale of two returns Issue Suppose you are predicting the mean annual return of an asset for some number of years.  To simplify the discussion, let’s buy into the fantasy that … Continue reading →

Read more »


Subscribe

Email:

  Subscribe