Posts Tagged ‘ Performance ’

Parallel processing with short jobs only increases the run time

December 27, 2013
By
Parallel processing with short jobs only increases the run time

Parallel processing has become much more important over the years as multi-core processors have become common place. From version 02.14 onwards, parallel processing has become part of the standard R installation in the form of the parallel package. This package… See more ›

Read more »

Calculating AUC the hard way

October 10, 2013
By
Calculating AUC the hard way

The Area Under the Receiver Operator Curve is a commonly used metric of model performance in machine learning and many other binary classification/prediction problems. The idea is to generate a threshold independent measure of how well a model is able to distinguish between two possible outcomes. Threshold independent here just means that for any model […]

Read more »

Discovering the quality of portfolio decisions

November 26, 2012
By
Discovering the quality of portfolio decisions

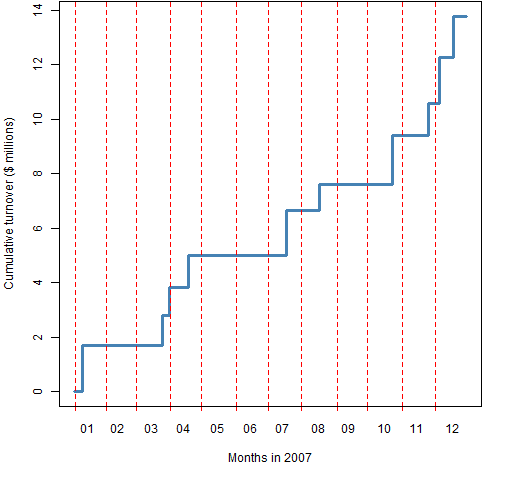
Performance analysis of an example portfolio. The portfolio We explore a particular portfolio during 2007.  It invests in S&P 500 stocks and starts the year with a value of $10 million.  Initially there are 50 names in the portfolio.  It also ends the year with 50 names but has up to 53 names during the … Continue reading →

Read more »

MCMC on the Raspberry Pi

July 7, 2012
By
MCMC on the Raspberry Pi

I’ve recently taken delivery of a Raspberry Pi mini computer. For anyone who doesn’t know, this is a low cost, low power machine, costing around 20 GBP (25 USD) and consuming around 2.5 Watts of power (it is powered by micro-USB). This amazing little device can run linux very adequately, and so naturally I’ve been […]

Read more »

Jackknifing portfolio decision returns

May 28, 2012
By
Jackknifing portfolio decision returns

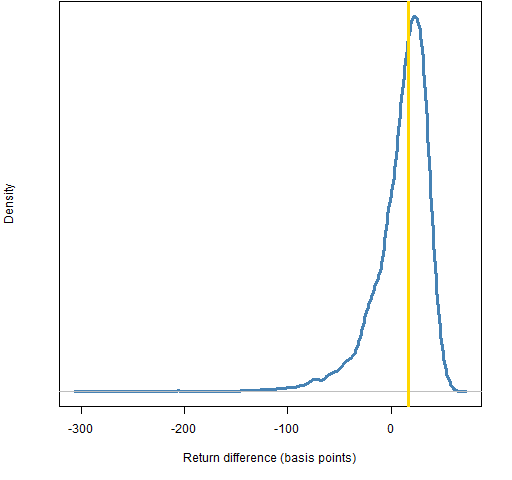
A look at return variability for portfolio changes. The problem Suppose we make some change to our portfolio.  At a later date we can see if that change was good or bad for the portfolio return.  Say, for instance, that it helped by 16 basis points.  How do we properly account for variability in that … Continue reading →

Read more »

Random portfolios: 6 steps to a better fund management industry

May 14, 2012
By

Only puny secrets need protection. Big discoveries are protected by public incredulity. – Marshall McLuhan Random portfolios have the power to improve the practice of asset management in several ways.  Here are six. 1) Measure active managers There is no convincing evidence that more than a handful of funds have consistently outperformed.  This should tell … Continue reading →

Read more »


Subscribe

Email:

  Subscribe