Posts Tagged ‘ Ledoit-Wolf shrinkage ’

Variance matrix differences

May 15, 2013
By
Variance matrix differences

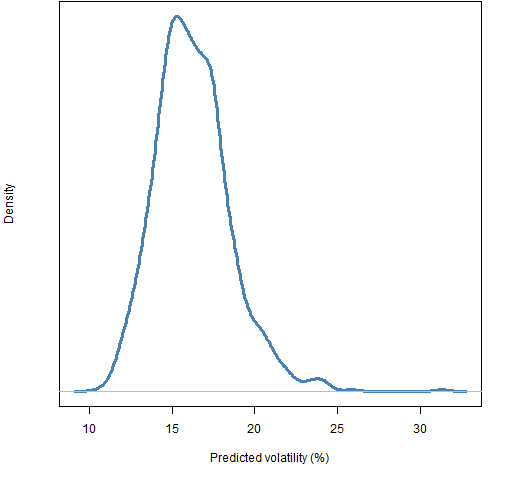
Torturing portfolios to give different volatilities between a factor model and Ledoit-Wolf shrinkage. Previously There have been posts on: “What the hell is a variance matrix?” factor models Ledoit-Wolf shrinkage Question Two of the several ways to produce an estimate of the variance matrix of asset returns is a statistical factor model and Ledoit-Wolf shrinkage.  … Continue reading →
Read more »

Predicted correlations and portfolio optimization

March 5, 2013
By
Predicted correlations and portfolio optimization

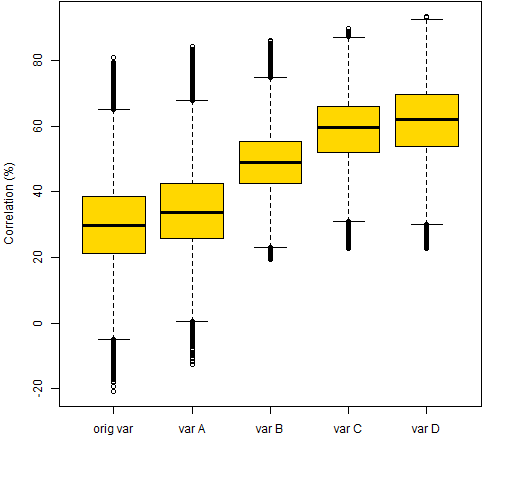
What effect do predicted correlations have when optimizing trades? Background A concern about optimization that is not one of “The top 7 portfolio optimization problems” is that correlations spike during a crisis which is when you most want optimization to work. This post looks at a small piece of that question.  It wonders if increasing predicted … Continue reading →

Read more »

Variability of predicted portfolio volatility

February 11, 2013
By
Variability of predicted portfolio volatility

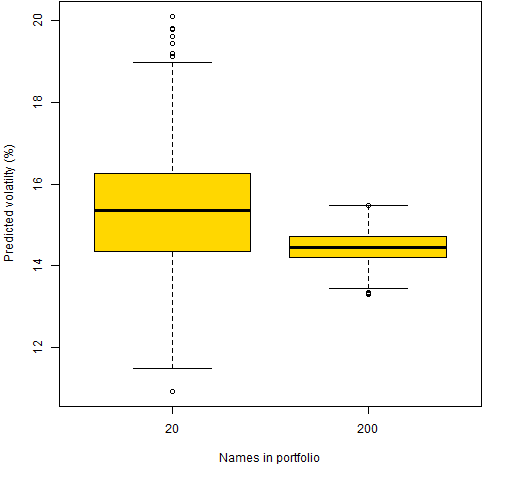
A prediction of a portfolio’s volatility is an estimate — how variable is that estimate? Data The universe is 453 large cap US stocks. The variance matrices are estimated with the daily returns in 2012. Variance estimation was done with Ledoit-Wolf shrinkage (shrinking towards equal correlation). Two sets of random portfolios were created.  In both … Continue reading →

Read more »

Correlations and postive-definiteness

May 22, 2012
By
Correlations and postive-definiteness

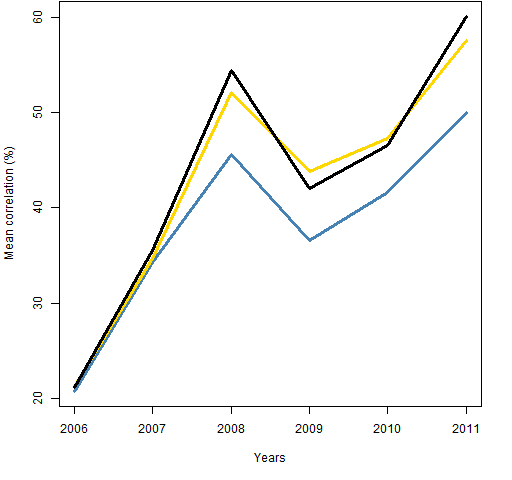
On the way to another destination, I found some curious behavior with average correlations. The data Daily log returns from almost all of the constituents of the S&P 500 for years 2006 through 2011. The behavior Figure 1 shows the actual mean correlation among stocks for the set of years and the mean correlation with … Continue reading →

Read more »


Subscribe

Email:

  Subscribe