Posts Tagged ‘ GMM ’

When Everything Old is New Again

May 19, 2017
By
When Everything Old is New Again

Some ideas are so good that they keep re-appearing again and again. In other words, they stand the test of time, and prove to be useful in lots of different contexts – sometimes in situations that we couldn’t have imagined when the idea first came ...

Read more »

Difference-in-Differences With Missing Data

January 9, 2016
By
Difference-in-Differences With Missing Data

This brief post is a "shout out" for  Irene Botusaru (Economics, Simon Fraser University) who gave a great seminar in our department yesterday.The paper that she presented (co-authored with Federico Guitierrez), is titled "Diff...

Read more »

The ivlewbel Package. A new way to Tackle Endogenous Regressor Models.

May 15, 2014
By
The ivlewbel Package. A new way to Tackle Endogenous Regressor Models.

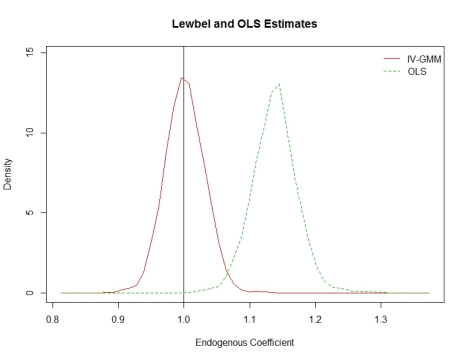
In April 2012, I wrote this blog post demonstrating an approach proposed in Lewbel (2012) that identifies endogenous regressor coefficients in a linear triangular system. Now I am happy to announce the release of the ivlewbel package, which contains a function through which Lewbel’s method can be applied in R. This package is now available […]

Read more »

IV Estimates via GMM with Clustering in R

April 1, 2014
By
IV Estimates via GMM with Clustering in R

In econometrics, generalized method of moments (GMM) is one estimation methodology that can be used to calculate instrumental variable (IV) estimates. Performing this calculation in R, for a linear IV model, is trivial. One simply uses the gmm() function in the excellent gmm package like an lm() or ivreg() function. The gmm() function will estimate […]

Read more »


Subscribe

Email:

  Subscribe