
Several years ago I wrote a number of posts about Logit and Probit models, and the Linear Probability Model LPM). One of those posts (also, see here) dealt with the problems that arise if you mis-classify the dependent variable in such models...

Several years ago I wrote a number of posts about Logit and Probit models, and the Linear Probability Model LPM). One of those posts (also, see here) dealt with the problems that arise if you mis-classify the dependent variable in such models...

Here are some of the papers that I've been reading recently. Some of them may appeal to you, too:Bampinas, G., K. Ladopoulos, &T. Panagiotidis, 2017. A note on the estimated GARCH coefficients from the S&P1500 universe. WP 17-09, Rimini C...

New Year's resolution - read more Econometrics!Bürgi, C., 2016. What do we lose when we average expectations? RPF Working Paper No. 2016-013, Department of Economics, George Washington University.Cox, D.R., 2016. Some pioneers of modern statistical th...
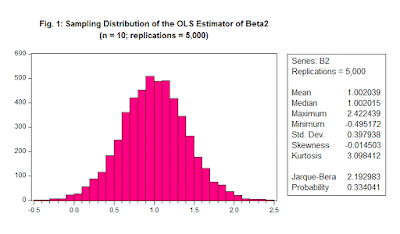
This post is the third in a series of posts that I'm writing about Monte Carlo (MC) simulation, especially as it applies to econometrics. If you've already seen the first two posts in the series (here and here) then you'll know that my intention is to ...
This post is the third in a series of posts that I'm writing about Monte Carlo (MC) simulation, especially as it applies to econometrics. If you've already seen the first two posts in the series (here and here) then you'll know that my intention is to ...
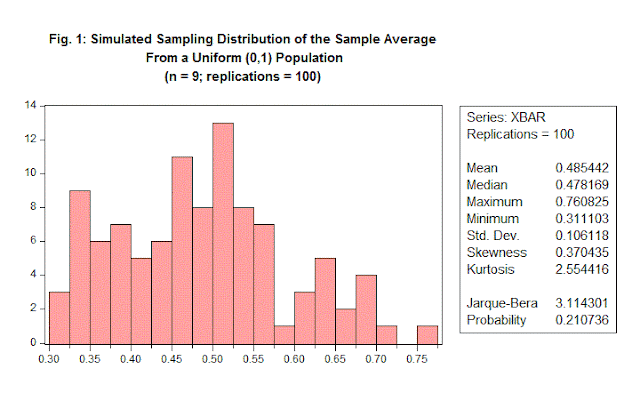
In the early part of my recent post on this series of posts about Monte Carlo (MC) simulation, I made the following comments regarding its postential usefulness in econometrics:".....we usually avoid using estimators that are are "inconsistent". This i...

A few days ago, the inaugural winner of the biennial International Prize in Statistics was announced.The first recipient of the new award is Sir David Cox, whose work is, of course, well known to econometricians.The award was made to Sir David for his ...

Ryan Godwin and I have a new paper - "Improved Analytic Bias Correction for Maximum Likelihood Estimators". You can download it from here.This paper proposes a modification of the Cox-Snell/Cordeiro-Klein bias correction technique that we've used in ou...

I began a recent post with the comment:"One thing that a lot of practitioners seem to be unaware of (or they choose to ignore it) is that in many of the common situations where we use regression analysis to estimate elasticities, these e...

In a recent post I discussed some aspects of estimating elasticities from regression models, and the interpretation of these values. That discussion should be kept in mind in reading what follows.One thing that a lot of practitioners seem to be unaware...
