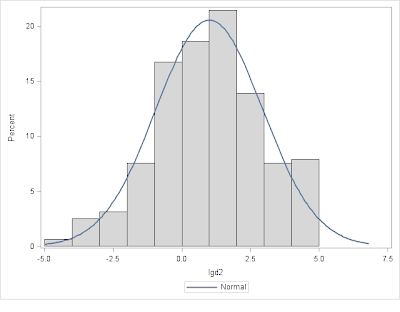
Loss Given Default (LGD) is a key business metric of risk in financial service. One unique feature of this metric is overdispersion and the other is multi-mode. Finite mixture model is an effective way to accommodate both. Multi-mode refers to the case...